Health
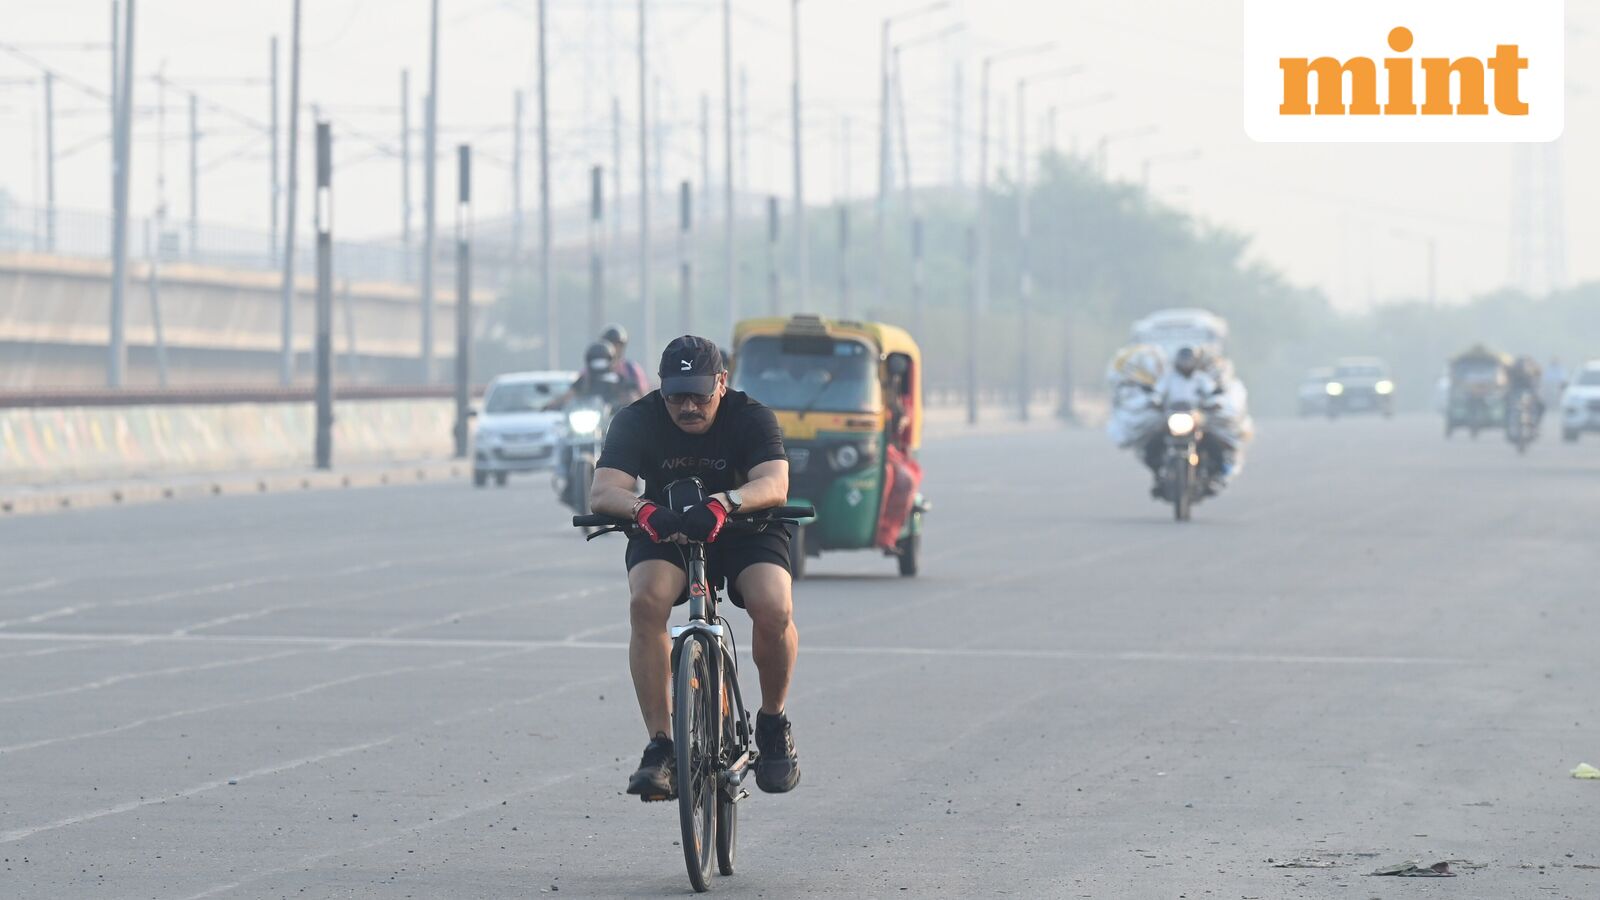
India seeks clearer evidence of air pollution's health impact as smog worsens
By Katherine Langford
Advertisement · Why this ad?
Marcus manages the day-to-day editorial workflow across all brands, coordinating coverage assignments and ensuring editorial standards are met. He previously served as city editor at the Pioneer Press and holds a degree in Political Science from Carleton College.
More from Marcus →
As the sun sets over Central Park, a couple sits on a bench, hands intertwined, reflecting on their lives. At 68 and 74, they are both healthy and active, yet a looming question hangs over them: what will happen to their life savings? With no children to inherit their wealth, they face a startling statistic — a 99% chance of outliving their savings. For many in their position, the answer might be to spend it all, but the implications are far more complex.
According to recent studies, aging couples without children are increasingly concerned about their financial futures. Many are discovering that traditional retirement planning may not suffice. As reported by MarketWatch, the average couple can expect to face significant expenses in healthcare and living costs as they age. With life expectancy rising, the risk of depleting savings is a serious concern.
For couples like John and Mary Smith, the decision to spend their savings becomes a practical consideration. "We’ve worked hard for decades, and we want to enjoy our retirement," John says. The couple, who have lived in New York City for over 40 years, have seen friends struggle with the financial burden of aging. They want to avoid that fate.
Financial experts recommend that couples in similar situations assess their spending habits. A well-structured budget can help manage expenses while still allowing for enjoyment. However, the fear of running out of money is palpable. Many seniors are left wondering how to balance enjoyment with the need for financial security.
In New York City, where the cost of living is notoriously high, this dilemma is particularly pressing. The Smiths often discuss strategies with their friends, many of whom are also childless couples facing similar challenges. They find solace in sharing experiences and advice, creating a small community of support that helps them navigate the complexities of retirement planning.
Health is a significant factor in financial planning for seniors. With advances in medicine, people are living longer but also facing higher healthcare costs. According to the CDC, healthcare expenses can consume a large portion of retirement savings. For John and Mary, staying healthy has been a priority, but they know that unforeseen medical issues could arise.
"We exercise regularly and eat well, but you can’t predict the future," Mary notes. The couple has opted for preventative care, which they believe will help mitigate costs down the line. They are also exploring long-term care insurance options to safeguard against potential future expenses.
Striking a balance between enjoying life and planning for the future is crucial. Financial advisors suggest that couples consider their lifestyle choices and how those choices impact their finances. For John and Mary, this means traveling and pursuing hobbies while still being mindful of their budget.
"We want to make memories, not just save money," John emphasizes. This mindset resonates with many couples in New York City, where the cost of living is high, but the desire to enjoy life remains strong. They often indulge in cultural experiences, such as attending Broadway shows or visiting art galleries, which they believe enrich their lives.
Moreover, the couple has become more conscious of their spending habits. They have learned to differentiate between needs and wants, allowing them to allocate resources for experiences that truly matter to them. This shift in mindset has not only eased their financial anxieties but has also deepened their appreciation for each moment they share together.
Living in a vibrant city like New York offers unique opportunities for social engagement, which can also alleviate some financial pressures. Community centers and local organizations provide resources for seniors, including financial planning workshops and health screenings. The NYC Department for the Aging offers programs aimed at helping seniors navigate their financial futures.
John and Mary have taken advantage of these resources, attending workshops that focus on financial literacy and health management. "It’s great to know we’re not alone in this journey," Mary explains. The couple has made friends through these programs, creating a support network that enriches their lives.
Additionally, they participate in local meetups that cater to seniors, where they engage in activities ranging from yoga classes to book clubs. This involvement not only helps them stay active but also fosters a sense of belonging in a city that can often feel isolating. The friendships they’ve formed have become a crucial part of their lives, providing emotional support and practical advice as they navigate their retirement years.
As John and Mary look ahead, they are not just focused on spending their savings but also on leaving a legacy — not necessarily a financial one, but one of love and commitment. They often volunteer at local charities, believing that giving back is just as important as financial planning.
"We want to make a difference in our community," John states. This perspective is shared by many couples without children, who find fulfillment in contributing to society rather than worrying about inheritance. Their volunteer work has allowed them to connect with younger generations, sharing their experiences and wisdom, which they find immensely rewarding.
Furthermore, they are exploring ways to document their journey through blogs and social media, hoping to inspire other couples in similar situations. They believe that sharing their story can help others see the value of community and the importance of making the most of life, regardless of financial circumstances.
The decision to spend or save is deeply personal. For John and Mary, it’s about embracing the present while preparing for the future. They are actively making choices that reflect their values, prioritizing experiences over material possessions.
In a world where financial security is often equated with success, couples like John and Mary remind us that true wealth lies in relationships and experiences. Their story serves as an inspiration for others in similar situations, encouraging them to live fully while being mindful of their financial realities.
In the end, John and Mary’s journey highlights the importance of thoughtful financial planning and the value of community support. As they navigate their golden years, they are learning to balance enjoyment with responsibility, leaving behind a legacy that transcends mere dollars and cents. Their approach serves as a reminder that life is not just about saving for tomorrow but living for today. Through their experiences, they continue to inspire those around them, fostering a sense of hope and resilience in a community that faces similar challenges.
By Katherine Langford
By Katherine Langford

By Marcus Chen
By Katherine Langford